ar
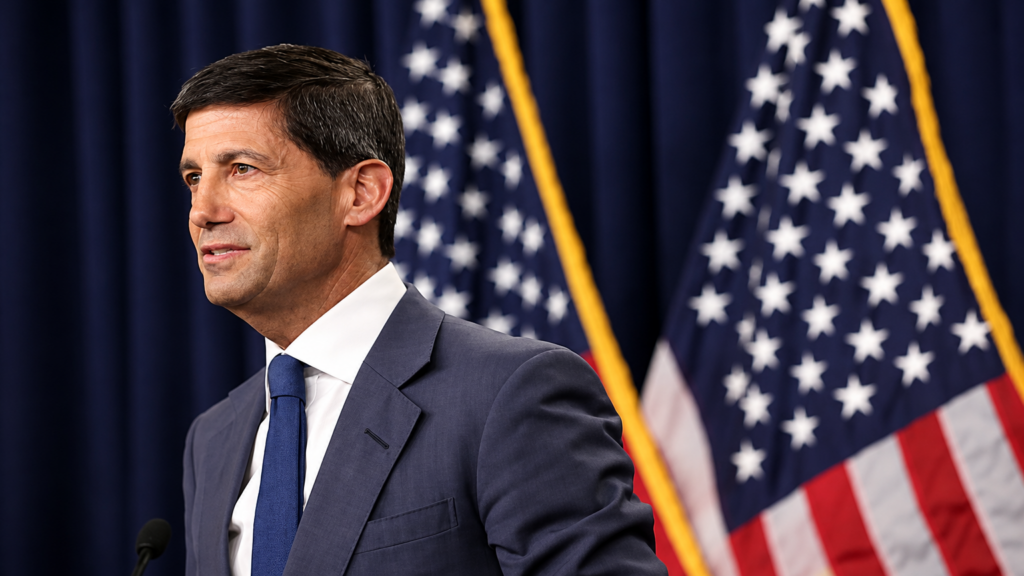
- Kevin Warsh’s Fed held rates for two straight meetings before delivering its first hike in September, the first increase since 2023.
- Warsh has deliberately scaled back forward guidance, a sharp departure from the approach markets grew used to under Jerome Powell.
- The October hold drew two dissents in favour of another increase, showing that September’s unanimous hike had not settled the debate over further tightening.
Kevin Warsh took over as Federal Reserve Chair on May 22, 2026, succeeding Jerome Powell, whose own final meeting as chair was closely watched for signs of where rates were headed next ⁽¹⁾.
Five months into his tenure, the clearest shift is not simply the level of interest rates. It is how little the Fed now says about where rates might go next.
A Hold, a Hike, and a Dropped Playbook
At his first meeting on June 17, the Federal Open Market Committee (FOMC) held the federal funds rate at 3.50% to 3.75% ⁽²⁾.
The post-meeting statement was shorter than its predecessors, reflecting Warsh’s preference for less forward guidance. He argued that the Fed should not be in the business of pre-committing to a policy path ⁽²⁾.
Asked directly about the months ahead, he told reporters: “I can’t give any forward guidance about what we’re going to do next” ⁽²⁾.
The July meeting followed the same pattern: another hold at 3.50% to 3.75%, this time by a 9-3 vote. Reserve Bank presidents Beth Hammack, Neel Kashkari and Lorie K. Logan dissented, favouring an immediate quarter-point increase ⁽³⁾.
The hold ended on September 16. The FOMC raised the federal funds rate by 25 basis points to 3.75% to 4.00%, its first increase since 2023. The decision was unanimous ⁽⁴⁾.
A Quieter Fed Than Powell’s
Powell’s final policy statement in April retained language about the “extent and timing of additional adjustments” to interest rates. Three officials supported holding rates but dissented over the statement’s easing bias, showing that the wording itself carried a signal about the likely direction of policy.
Warsh’s first statement in June was shorter and removed forward guidance. He said the committee considered such guidance poorly suited to the current environment and declined to signal its next move.
Data dependence already guided Powell’s approach. April’s statement explicitly tied future decisions to incoming information, the economic outlook and the balance of risks.
Warsh argues that market prices are more informative when investors respond independently to economic developments. If prices mainly reflect the Fed’s guidance, policymakers risk reading their own views back through markets.
This approach could give the Fed more independent information, while leaving investors less certain about how the committee will respond to new data.
The quarterly projections still offer insight into policymakers’ thinking. September’s dot plot showed 16 of 18 participants projecting further tightening before year-end. Those individual projections provide information about the outlook, but they do not establish an agreed policy path.
Inflation Is the Central Concern
At his Jackson Hole address on August 28, Warsh set out what he called his standard: “We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed” ⁽⁵⁾.
The inflation data available at the October meeting help explain that focus. Core PCE inflation stood at 3.0% in August, while headline CPI inflation reached 3.7% in September. Gasoline accounted for more than half the monthly CPI increase. ⁽⁶⁾
Higher energy prices amid Middle East tensions added to the pressure ⁽⁷⁾.
In 1994, the Fed under Alan Greenspan surprised bond markets with a tightening cycle that was not fully anticipated, triggering a sharp selloff that became known as the bond market massacre ⁽⁸⁾.
The parallel is not exact; the 1994 Fed gave almost no advance signal at all, while Warsh’s committee still publishes a statement, a press conference and a quarterly SEP. Less forward guidance shifts more of the burden onto incoming data, interest-rate expectations and market prices.
The October meeting showed the challenge between higher interest rates and sticky inflation. Warsh acknowledges that financing conditions had tightened but stopped short of calling them tight, which indicates that the committee sees some restraint taking effect without concluding that it is sufficient to return inflation back to its target.
A Split Committee, A Muted Chair
The pattern continued on October 28. The FOMC voted 10-2 to hold the federal funds rate at 3.75% to 4.00%, with Governor Lisa D. Cook and Cleveland Fed President Beth Hammack dissenting in favour of a quarter-point increase ⁽⁹⁾.
Hawkish dissent had surfaced in July, gone quiet for the unanimous September hike, and resurfaced in October, evidence that the committee remains split on how much more tightening the inflation data justify.
Warsh said politics played no role in the decision, delivered a week ahead of the US midterm elections ⁽⁹⁾. He also announced a change to the FOMC calendar. Eight meetings will remain scheduled annually, but one in 2027 will focus exclusively on monetary policy strategy, with no rate vote or policy statement anticipated. He expects two such meetings in 2028. ⁽⁹⁾
Since taking office, Warsh has opened a broad examination of the Fed’s balance sheet, its communications practices, the data it relies on and its inflation framework.
Conclusion
Five months into Warsh’s tenure, markets have three lessons to consider:
- Policy is data-dependent, not tied to a pre-set calendar. The September increase followed two consecutive holds, while the October vote, showed the committee still disagrees on how much further tightening is warranted.
- The shift toward saying less looks structural, not temporary. Shorter statements, the announced change to the meeting calendar and a broad internal review all point the same way: Warsh is reducing explicit signals about future policy decisions.
- Inflation remains the test Warsh set for himself. His own Jackson Hole standard, that underlying inflation must be “clearly and at sufficient speed” moving to target, is the benchmark against which the next hold or hike will be read, with or without an explicit signal beforehand.
The September Summary of Economic Projections indicated that 16 of the 18 participants expected at least one further rate increase in 2026 ⁽⁴⁾. That is a projection, not a commitment.
Warsh’s approach leaves the timing dependent on how the data evolve, with inflation remaining central to the decision.