ar
With the Fed not meeting again until December, this week the data does the talking.
US inflation figures land on Tuesday and Friday, the UK gets its first look at third-quarter growth on Thursday, and oil traders have four major reports to work through before the weekend.
Calendar Events
- US CPI – Nov. 10
- UK Prelim Q3 GDP – Nov. 12
- Eurozone Flash Q3 GDP – Nov. 13
- US PPI – Nov. 13
Top Things to Watch
1. US Stock Futures Rise as December Hike Bets Hold
S&P 500 and Nasdaq-100 futures were both up about 0.6% earlier today, following Friday’s partial rebound in tech stocks. The Nasdaq Composite gained 1.1% on Friday after Thursday’s 5.5% slide, but still ended the week down 3.4%.
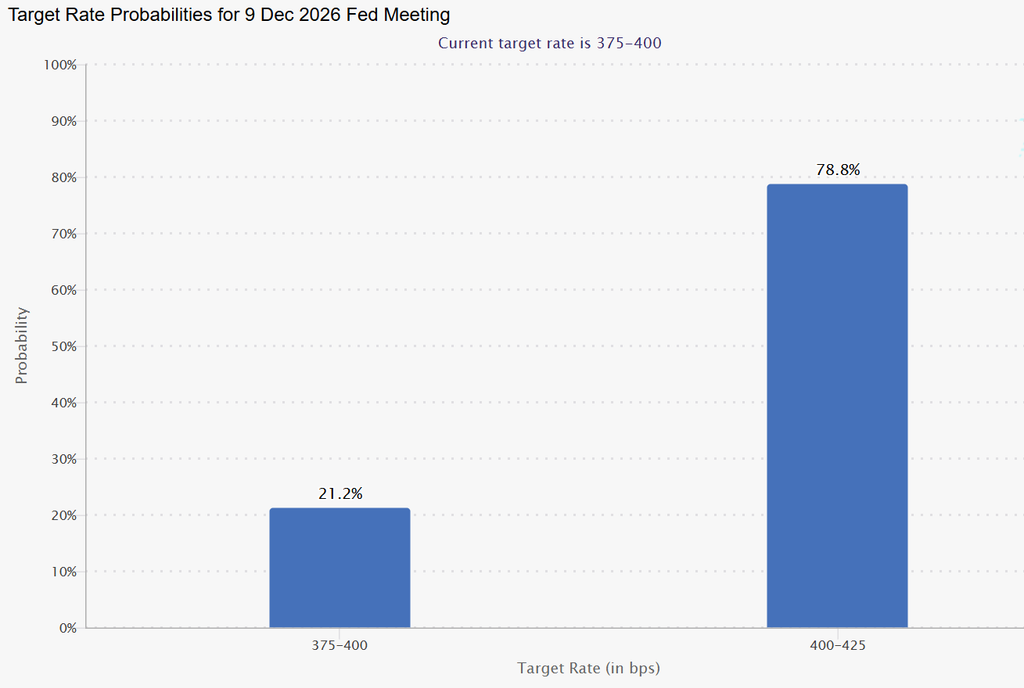
Friday’s jobs report showed US payrolls rose by 165,000 in October, versus 65,000 expected, while unemployment fell to 4.1%. Markets were still pricing about an 80% chance of a December Fed hike early Monday, up from roughly 67% on Thursday. Tuesday’s CPI is the next test for December rate expectations.
2. US CPI & PPI
After September’s 0.6% jump in consumer prices, Tuesday’s October CPI will show whether that was a one-off. Economists expect a softer 0.3% rise this time. Producer prices follow on Friday, forecast at 0.4% after a 1.3% surge the month before.
Keep a close eye on core. Last year’s government shutdown left no October baseline for the usual annual figures, so the monthly core reading carries more weight than normal. A dip to the expected 0.2% from 0.3% would point to price pressures easing beyond energy.
3. A Packed Week for Oil
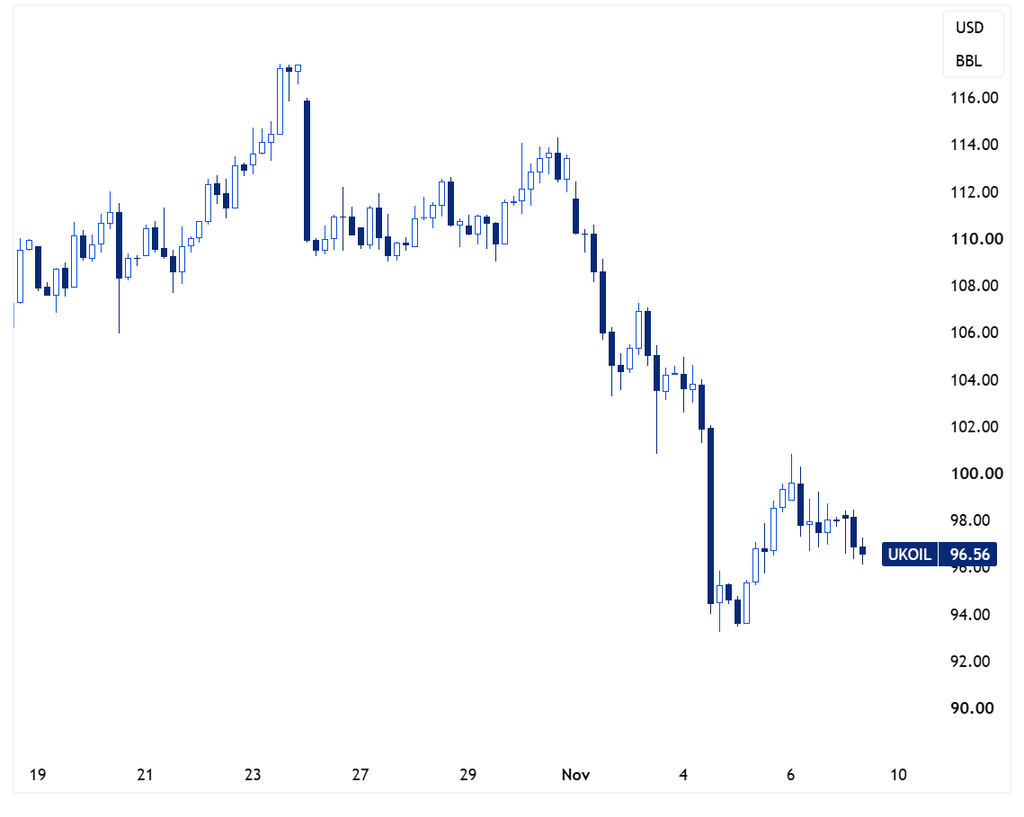
Brent steadied near $98 a barrel earlier today after last week’s sharp sell-off. US President Donald Trump signaled that fresh strikes on Iran were unlikely as long as talks made progress, while new reports of attacks on ships near the Strait of Hormuz kept supply concerns alive.
The EIA updates its outlook on Tuesday, followed by OPEC’s monthly report on Wednesday, US crude inventories on Thursday and the IEA’s report on Friday. The IEA previously projected a global oil deficit through year-end. Friday’s update will show whether the agency still expects a shortfall and how the latest attacks factor into the outlook for Gulf exports.
4. UK Q3 GDP Figures
Thursday’s first estimate of Q3 GDP is the first real test since the Bank of England raised rates to 4.00% last week. The Bank and the market are both expecting growth of 0.7%, up from 0.5% in the second quarter.
The catch is that the Bank’s own business surveys pointed to just 0.2%. That makes the detail more important than the headline, with household spending and business investment showing whether the growth is as strong as it looks.