

 ar
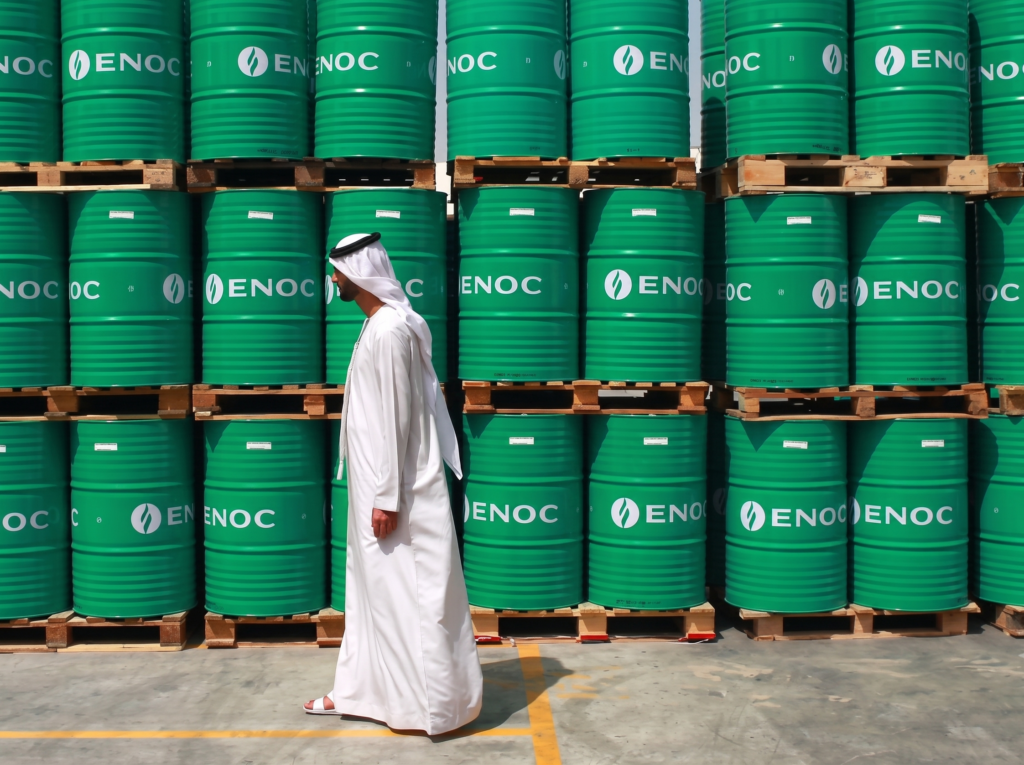
- Oil revenue and market sentiment are the two direct channels linking oil prices to the UAE economy, even as non-oil sectors now generate more than three-quarters of real GDP.
- Abu Dhabi and Dubai carry very different oil exposure, so a single move in oil prices can affect the two emirates, and their stock exchanges, in different ways.
- Diversification, the dirham’s dollar peg, and large fiscal reserves limit how far oil price swings travel through the economy. They do not remove the link entirely.
Oil prices affect the UAE economy mainly through two channels. The first is government revenue and the second is market sentiment.
When oil prices rise, government income tends to improve and investor confidence in Gulf markets tends to firm up. When oil prices fall, both effects tend to work in reverse.
While the relationship is real, it has clearly weakened. Non-oil activities made up 77.3% of the UAE’s real GDP in the first quarter of 2025, the highest share on record. ⁽¹⁾
So oil still matters. It just matters less than it used to.
How Oil Prices Move the UAE Economy
The clearest transmission channel is public revenue, especially in Abu Dhabi. Higher oil prices improve fiscal space, support state-linked investment, and can strengthen confidence across the wider UAE economy.
Economists track this through the fiscal breakeven price, the oil price a government needs to balance its budget. The IMF put the UAE’s fiscal breakeven price at roughly $50 a barrel for 2025 ⁽²⁾, well below where Brent has traded for most of the year.
A lower breakeven price means the government needs less from each barrel to stay in balance, a sign of how far diversification has come.
The second channel runs through market sentiment.
Energy-linked stocks on the Abu Dhabi Securities Exchange, including ADNOC’s listed units, tend to track oil price direction closely. That sentiment can spill into broader GCC risk appetite, reaching currencies, bonds, and equities across the region.
This is part of why the UAE’s exit from OPEC in May after 59 years mattered beyond the group’s supply quotas. ⁽³⁾
It signaled that Abu Dhabi wanted to set its own production path. ADNOC has been raising crude capacity toward 5 million barrels a day by 2027, backed by a $150 billion investment plan. ⁽⁴⁾
Abu Dhabi and Dubai: Two Different Exposures
Not every part of the UAE feels an oil move the same way.
Abu Dhabi produces nearly all of the country’s crude. Oil and oil-linked activity made up roughly 44% to 46% of the emirate’s nominal GDP through 2025. ⁽⁵⁾
The Abu Dhabi Securities Exchange reflects that weighting, with energy names carrying real influence over the index.
Dubai is different. Oil contributes less than 1% of Dubai’s GDP today. The Dubai Financial Market leans instead on real estate, banking, and financial services.
A sharp oil move can still reach Dubai indirectly, through regional sentiment or federal spending, but the direct exposure is small.
When Oil Prices Lose Their Grip
Three things limit how far an oil price move can travel through the UAE economy.
The first is diversification itself. When non-oil sectors generate more than three-quarters of output, a swing in oil prices touches a much smaller share of the economy than it did a decade ago.
The second is the dirham’s peg to the US dollar, fixed at 3.6725 since 1997. ⁽⁶⁾ Oil is priced in dollars, and the dirham does not float against it. Oil price swings do not translate into currency volatility the way they might in a country with a floating exchange rate.
The third is fiscal reserves. Many oil exporters built up savings during the 2014 to 2016 oil price crash, precisely so a future price drop would not force immediate spending cuts.
The UAE has followed the same approach, giving it room to smooth spending even when oil revenue softens.
PwC’s Chief Economist, Richard Boxshall, noted that “fiscal resilience today means adaptability,” pointing out that lower oil prices test buffers but ultimately reinforce the UAE’s commitment to reform and diversification.
Falling Oil Prices Can Also Move Markets
The mechanism works in both directions. Brent crude fell back toward $72 in early July after trading above $126 during the height of the earlier Hormuz disruption, before renewed tensions pushed prices higher again. ⁽⁷⁾
At current prices, the UAE remains well above its fiscal breakeven level, so the near-term budget picture stays comfortable.
If prices were to fall further and stay lower for a sustained period, the pressure would likely show up first in energy-linked equities, and second in the pace of government spending.
It would not show up through currency volatility because of the dirham’s dollar peg. But it could still affect fuel and transport costs, since UAE petrol and diesel prices are linked to global energy prices.
That, in the end, is what the buffers were built for. Not to erase oil’s influence, but to keep it manageable.


