

 ar
- The US dollar continues to weaken on geopolitical tensions that kept markets on edge towards US assets, while data showed that inflation remains persistent.
- The Australian dollar emerged as a winner among the G10 currencies this week, with strong data reinforcing expectations of a more hawkish RBA.
- Precious metals hit new record highs, posting their strongest week since 2020 on rate cut expectations from the Federal Reserve and geopolitical tensions.
Global markets experienced a turbulent week, with the US dollar heading lower after President Trump reversed course on proposed tariffs against Europe.
Precious metals climbed to fresh record highs, supported by earlier geopolitical tensions, while currency markets remained choppy following a wave of high-impact economic data. Key releases included US core PCE and GDP figures, alongside labour-market and PMI data from Australia.
Shifting policy expectations from the Reserve Bank of Australia and the Bank of Japan added to the uncertainty, shaping market sentiment through the week.
Policy Whiplash Triggers Dollar Weakness
The US dollar index is set for a weekly drop of 1%, ending a volatile week following major geopolitical shifts that kept investors nervous towards US assets.
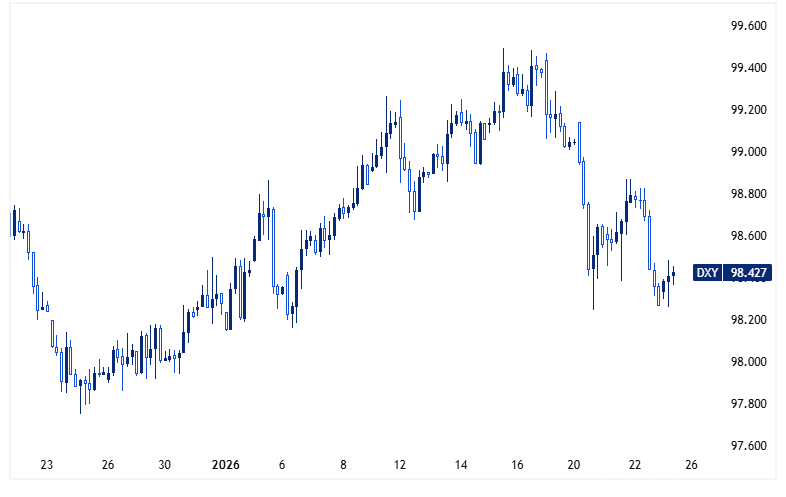
DXY 4H Chart / Source: TradingView
The week began with President Trump hitting tariff threats at eight European countries over their opposition to his plans of purchasing Greenland, only to reverse course entirely after his Wednesday appearance in Davos.
The change of heart came after securing what officials called a framework agreement with NATO, though the details remain conspicuously under wraps, keeping markets guessing.
Concerns also grew that Europe might leverage its substantial US asset holdings, with a Danish pension fund announcing it would exit its Treasury positions, adding to market uncertainty. ⁽¹⁾
Moving on to the domestic front, the US core PCE index came in higher than expected at 2.8% YoY against its forecast of 2.7%. The final Q3 GDP also showed robust growth at 4.4%. The data indicates an economy continuing to expand, with consumer spending ahead of inflation despite a somewhat softening labor market. ⁽²⁾
All eyes turn to next week’s Federal Reserve meeting, where the central bank is expected to hold rates at 3.75%. Fed policymakers remain divided on whether to keep interest rates on hold in order to bring inflation down or cut rates to support the weakening labor market. ⁽³⁾
Strong AUD Data Fuels Hawkish Repricing
The Australian dollar emerged as a standout performer this week, climbing to near 16-month highs on the back of robust jobs data that fueled expectations for a near-term rate hike. Upbeat PMI figures added further momentum to the rally.
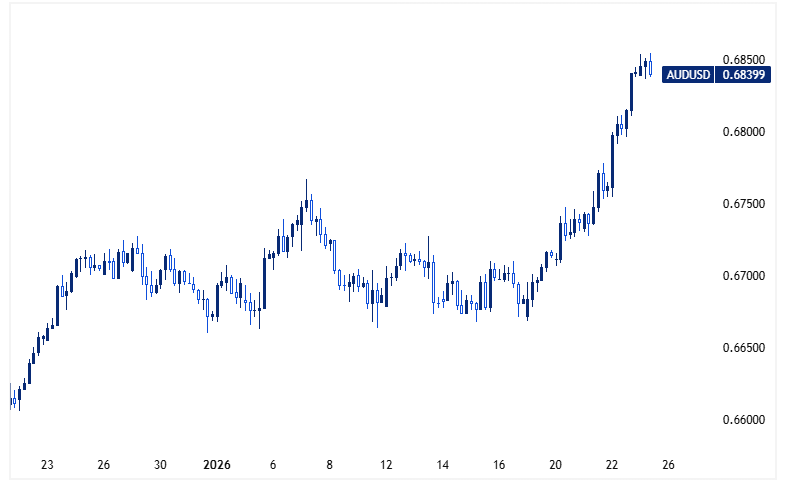
AUD/USD 4H Chart / Source: TradingView
Flash PMI data remained in expansion territory for 16 months straight, coming in at 55.5. Labor market data also showed robust numbers, with the unemployment rate unexpectedly falling to a seven-month low at 4.1%. ⁽⁴⁾
However, inflation isn’t moving. This led to more hawkish signals from the Reserve Bank of Australia and has brought more expectations for rate hikes. ⁽⁵⁾
BOJ Stays Put as Political Uncertainty Looms
The Japanese yen remained pressured after the Bank of Japan kept interest rates steady at 0.75%. The BOJ reaffirmed that it is still committed to raising rates if economic and price forecasts align.
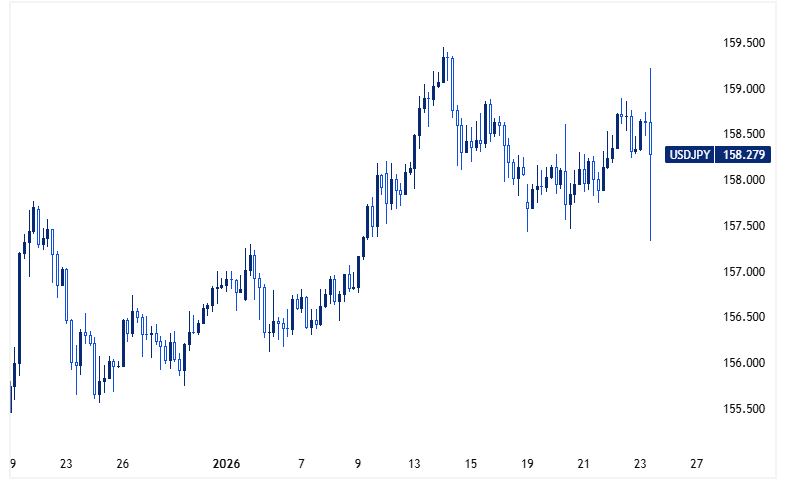
USD/JPY 4H Chart / Source: TradingView
Traders are worried that the yen could weaken further if the Bank of Japan dials back Governor Ueda’s signals on future rate hikes, especially as fiscal concerns have already weighed on the currency. ⁽⁶⁾
Prime Minister Sanae Takaichi is preparing to dissolve parliament and call a snap election to consolidate power and pursue increased spending.
Meanwhile, markets are closely monitoring potential currency intervention as the yen approaches the key 160 level.
Precious Metals Continue Their Path Higher to New Record Highs
Both gold and silver posted another easy week, hitting fresh record highs earlier today, with gold climbing above $4,950/oz and silver surging nearly 3% toward $99/oz earlier today. These precious metals are on track for their strongest week since March 2020.
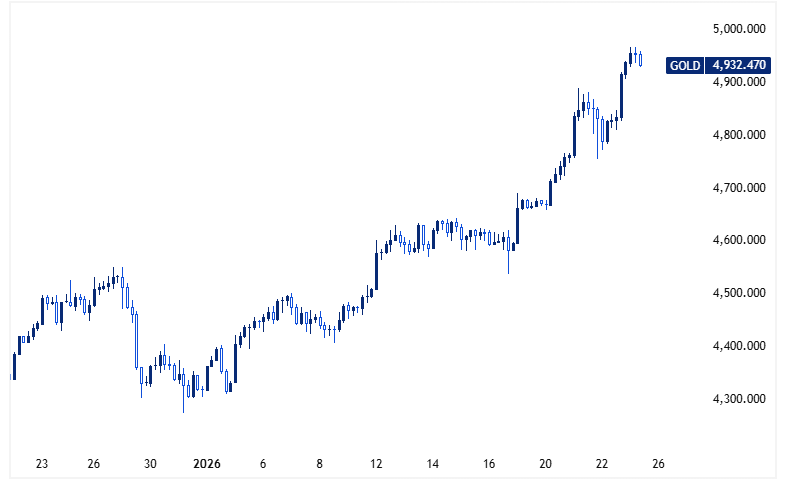
Gold 4H Chart / Source: TradingView
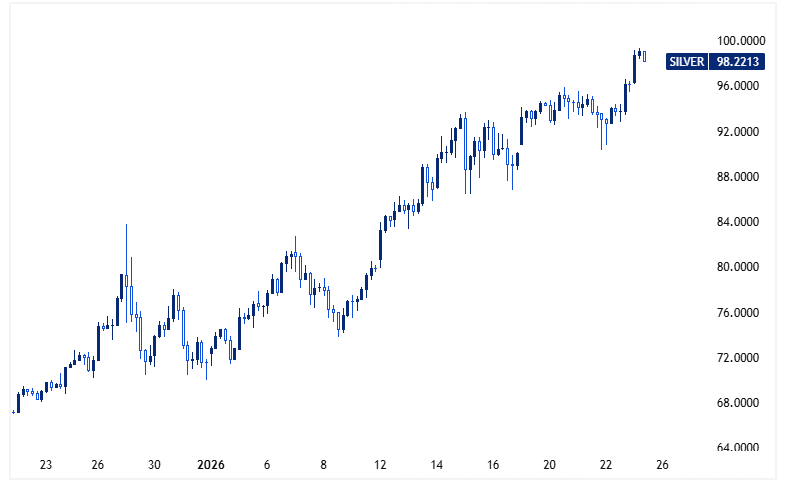
Silver 4H Chart / Source: TradingView
The surge was driven by a weaker US dollar after the tensions that took shape earlier this week between the US and Europe, with rising concerns that Europe could use its US assets as leverage against the US.
The Fed is expected to hold rates next week, with two rate cuts priced in this year. However, with Jerome Powell’s term as Fed Chair nearing its end, expectations could shift quickly if President Trump opts for a more dovish successor. ⁽⁷⁾


