

 ar
The Fed and the ECB both raised rates last month. This week, we find out what they were really saying behind closed doors.
Meanwhile, PepsiCo and Delta give us a look at whether consumers are still spending as prices bite. French debt concerns and oil supply developments also shape the week’s market outlook.
Calendar Events
- US ISM Services PMI – Oct. 5
- FOMC Meeting Minutes – Oct. 7
- ECB Meeting Minutes – Oct. 8
- Canada Unemployment Rate – Oct. 9
- US Consumer Sentiment – Oct. 9
- US Inflation Expectations – Oct. 9
Top Things to Watch
1. Slower Hiring, Stubborn Inflation
US employers added just 29,000 jobs in September, while the unemployment rate rose to 4.2%. Softer jobs and inflation data eased expectations for an October Fed hike, although core PCE remained at 3% and consumer spending stayed resilient.
Eurozone inflation reached 3.8%, driven largely by energy costs, while US Treasury yields rebounded after an initial decline. Markets now weigh slower hiring against persistent inflation ahead of central bank minutes and corporate earnings.
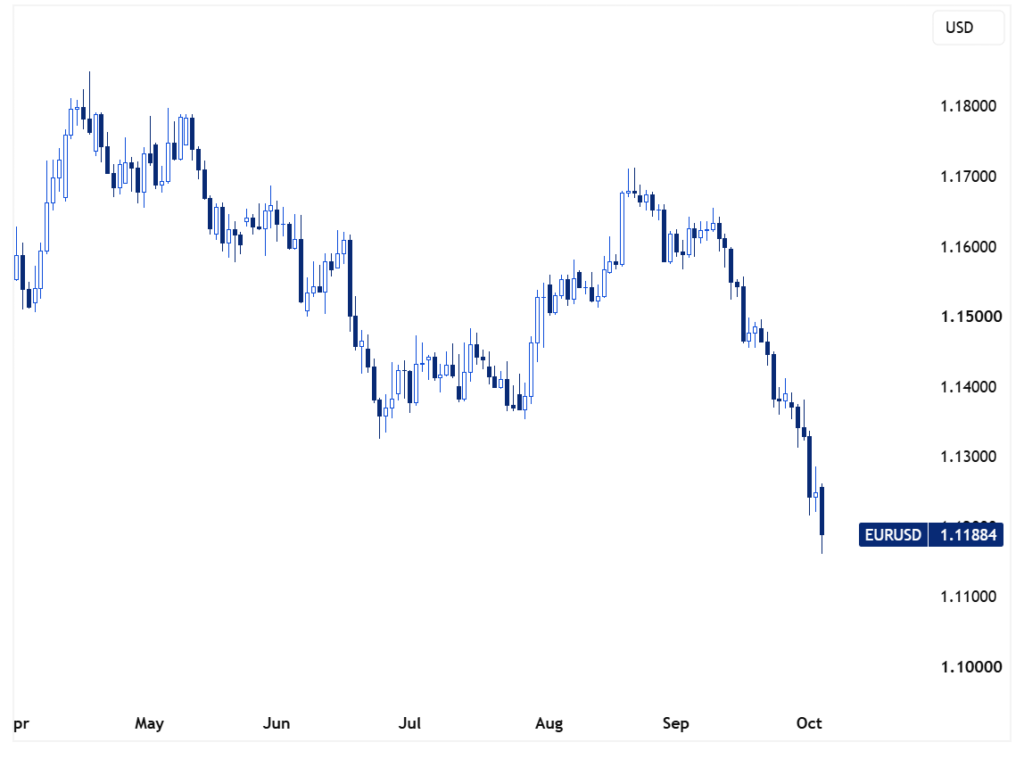
French debt concerns remain in focus at the start of the week, with elevated borrowing costs and political uncertainty weighing on the euro, which hit a 17-month low earlier today.
2. Oil Relief Meets Supply Risks
Oil slipped earlier today as recovering Middle East crude exports and the G7’s planned release of 100 million barrels of crude and fuel eased supply concerns. President Trump also ruled out a US diesel export ban.
OPEC+ agreed yesterday to keep November production targets unchanged. Attention now turns to reserve-release timing and threats to energy infrastructure.
3. FOMC & ECB Meeting Minutes
In September, the Fed hiked for the first time in three years, lifting rates by 25 basis points to 3.75%–4.00%. A week earlier, the ECB did the same, taking its deposit rate to 2.50%.
On Wednesday and Thursday, we get the minutes from both meetings. The big question is how many policymakers think one hike is enough, and how many are already eyeing the next one.
With the Fed deciding again on October 28 and the ECB on October 29, these minutes could reset expectations fast.
4. PepsiCo & Delta Airlines Earnings
PepsiCo kicks off Thursday before the open, with EPS expected around $2.32. Revenue rose 6.4% to $24.18 billion last quarter, but North American shoppers stayed cautious. Can price tweaks and strong overseas sales keep the growth coming?
Delta follows Friday, with EPS forecast at $2.03. Last quarter it beat estimates, but profits still dropped 26% as fuel costs took a bite. With oil near $100, the question is whether travellers keep flying and paying up for it.


