

 ar
Markets are starting the week with a shift in tone, as geopolitical tensions re-escalate and push risk back into focus, while earnings and macro data continue to shape the broader outlook.
A fragile ceasefire in the Middle East is once again under strain, pushing oil back into focus as geopolitical risks re-emerge, while a heavy lineup of earnings and key data releases will test whether the broader macro picture is stabilizing or still under pressure.
Here’s what’s on deck.
Calendar Events
- People’s Bank of China Interest Rate Decision – Apr. 20
- Canada CPI – Apr. 20
- New Zealand CPI – Apr. 21
- UK Claimant Count Change – Apr. 21
- UK Unemployment Rate – Apr. 21
- US Retail Sales – Apr. 21
- UK CPI – Apr. 22
- Eurozone Flash S&P PMI – Apr 23
- UK Flash S&P PMI – Apr 23
- US Flash S&P PMI – Apr 23
- UK Retail Sales – Apr 24
Top Things to Watch
Oil Rebounds — Tensions Push Risk Premium Higher
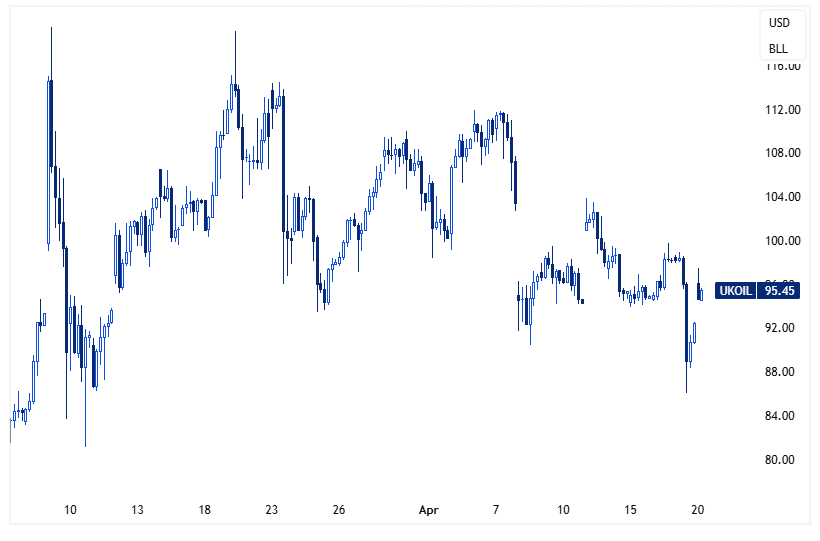
Crude oil prices moved higher earlier today as geopolitical tensions escalated sharply, with the US and Iran edging closer to renewed conflict following attacks on commercial shipping in the Strait of Hormuz.
The situation intensified after Iran targeted vessels over the weekend, prompting a US naval response and the seizure of an Iranian-linked ship, while the tone from Washington signaled the risk of further escalation. With the ceasefire set to expire and uncertainty around renewed negotiations, markets are once again pricing in a rising geopolitical risk premium tied to potential supply disruptions.
Earnings Wave — What Are Corporates Signaling Now?
Earnings season continues with Tesla, IBM, Boeing, and AT&T reporting Wednesday, followed by Amazon and Intel on Thursday.
The focus is not just on results but on what companies say about demand, margins, costs, and spending plans, with guidance likely to matter more than headline numbers.
Fed Signal — Warsh Testimony in Focus
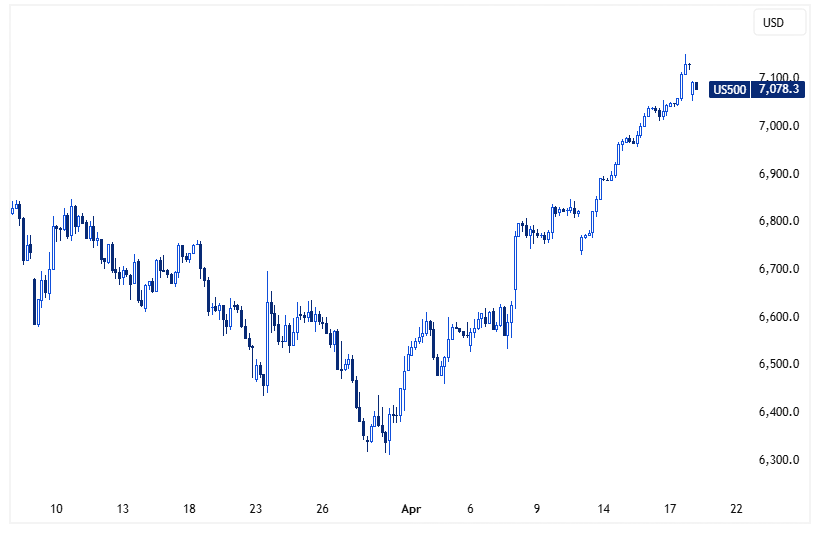
All eyes turn to Kevin Warsh on Tuesday as he testifies before the Senate Committee on Banking at a sensitive time, with Powell’s term nearing its end and policy uncertainty rising.
With energy-driven inflation creeping back and growth softening, Warsh’s tone will be key, as a dovish tilt could bring forward rate cut expectations, while inflation concerns may keep policy tighter for longer.
UK Jobs & Inflation — A Tight Balancing Act
Tuesday’s UK labor market data is expected to show unemployment near 5.2% with hiring momentum easing, signaling a gradual loosening in the labor market.
Wednesday’s CPI, currently around 3%, could rise on higher energy prices, leaving the Bank of England balancing slowing growth against still-sticky inflation.
Flash PMIs — Reality Check on Global Growth
Thursday’s global flash PMIs will provide one of the clearest near-term reads on underlying growth momentum.
After weeks dominated by geopolitical developments, attention now shifts back to whether the real economy is beginning to reflect those pressures.
The key question for markets is whether activity is holding up despite elevated energy costs.
Recent data has pointed to a mixed picture, with services showing relative resilience while manufacturing remains more exposed to downside risks.
With oil still elevated, these releases will be critical in assessing whether the shock is starting to filter through to broader economic activity or if growth is proving more resilient than expected.


