

 ar
With a new trading week comes new opportunities. So, we’ve gathered insights for the week ahead that highlight the current trends, scheduled events and potential movers to watch. Let’s get started.
Calendar Events
UK Unemployment Rate – Jan. 13
UK Employment Change – Jan. 13
UK Claimant Count Change – Jan. 13
UK Average Hourly Earnings – Jan. 13
US CPI – Jan. 13
US PPI – Jan. 14
US Retail Sales – Jan. 14
UK GDP – Jan. 15
Top Things to Watch
Q4 Earnings Kick-Off, Starting with Big Banks
Attention turns to Q4 earnings, with major US banks including JPMorgan Chase, Goldman Sachs, and Bank of America set to report, offering an early read on corporate profitability and financial conditions. Results will be closely watched for signals on trading revenue, investment banking activity, loan growth, and credit quality, helping shape expectations for the broader earnings season, bank stocks, and overall risk sentiment.
Geopolitical Risks Keep Volatility Elevated
Rising geopolitical tensions are increasing uncertainty across global markets, leading investors to demand higher risk premiums and adopt a more defensive stance. This environment has supported safe-haven assets such as gold and the US dollar, driven volatility in energy prices on supply-risk concerns, and boosted defense-related stocks, while broader equities remain sensitive to sudden headlines and shifts in risk sentiment.
US Inflation Data in Focus
Financial markets will closely watch December’s US inflation data this week, as it could influence the Federal Reserve’s next policy decision. The CPI report on Tuesday will shed light on consumer price pressures, while the PPI data on Wednesday will offer insight into producer-level costs. Both reports will shape interest rate expectations, the US dollar, and overall market sentiment.
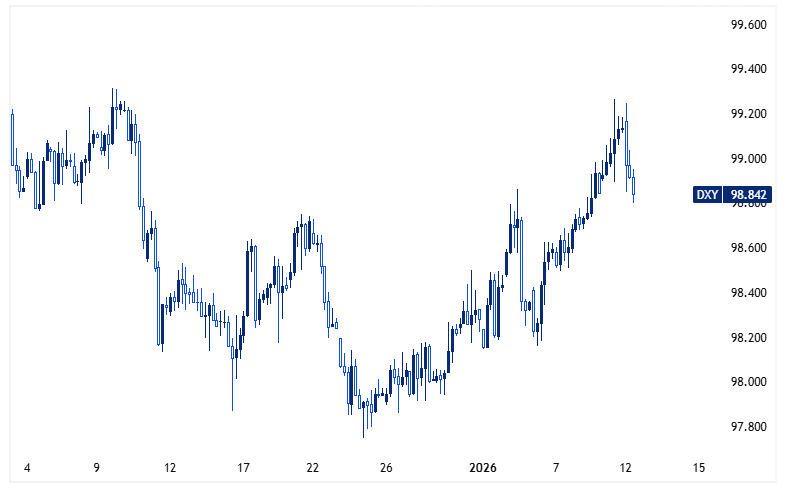
DXY 4H Chart / Source: TradingView
UK GDP in Focus: Key Test for Economic Momentum
Markets will turn their attention to the monthly UK GDP report due on Thursday, which will provide an important read on economic activity toward year-end. The data will be closely monitored for signs of sustained growth or renewed weakness, with direct implications for Bank of England policy expectations, sterling, and broader UK market sentiment.
Key Eurozone Data to Shape Investor Sentiment
Markets will also focus of Eurozone data this week, with releases on investor confidence, industrial production, and German CPI shaping outlook. Investor confidence will offer insight into risk appetite and growth expectations, industrial production will highlight the health of the region’s manufacturing sector, while Germany’s CPI will be key for assessing underlying inflation trends and ECB policy expectations, with potential implications for the euro and regional assets.


