

 ar
With a new trading week comes new opportunities.
So, we’ve gathered insights for the week ahead that highlight the current trends, scheduled events and potential movers to watch. Let’s get started.
Calendar Events
Germany GDP – Nov.25
US PPI – Nov.25
US Retail Sales – Nov.25
US CB Consumer Confidence – Nov.25
Australia CPI – Nov.26
New Zealand Interest Rate Decision – Nov.26
UK Autumn Budget – Nov.26
US Prelim Q3 GDP – Nov.26
US Core PCE Index – Nov.26
Eurozone Consumer Confidence – Nov.27
Japan BOJ CPI – Nov.28
Germany Retail Sales – Nov.28
Germany CPI – Nov.28
Switzerland GDP – Nov.28
Canada GDP – Nov.28
Top Things to Watch
Key US Data in Focus
High-impact US data is set to dominate the week, with September PPI and retail sales on Tuesday, followed by preliminary Q3 GDP and Core PCE on Wednesday. After weeks of uncertainty, shifting rate bets, and Fed commentary without new numbers to back it up, these releases will finally give markets the clarity they’ve been waiting for and could rapidly reset expectations for December’s Fed decision and the direction of US assets.
Gold Holds Steady as Markets Await Fresh Direction
Gold remained in a tight range as traders wait for clearer signals from upcoming US data and interest-rate expectations. After recent volatility, prices have stabilized, with traders also watching the US dollar for direction before making bigger moves.
Markets Brace for the UK Autumn Budget
The UK Autumn Budget will be unveiled on Wednesday, setting out the government’s latest plans for taxes, spending, and the broader economic outlook. Traders will be watching closely to see whether the budget delivers a confident, credible path for managing debt without putting pressure on growth. A cautious or unclear plan could slow GBP’s momentum, while stronger pro-growth measures may help lift sentiment.
RBNZ Decision in Focus as Rate Cut Expected
The Reserve Bank of New Zealand meets on Wednesday and is expected to deliver a 25-basis-point rate cut. With inflation still elevated and the economy losing momentum, policymakers will outline their updated view on interest rates. Markets will be watching for hints on whether the RBNZ plans to hold steady after this move or consider additional cuts, given the potential impact on the New Zealand dollar.
Trending Now: USDJPY
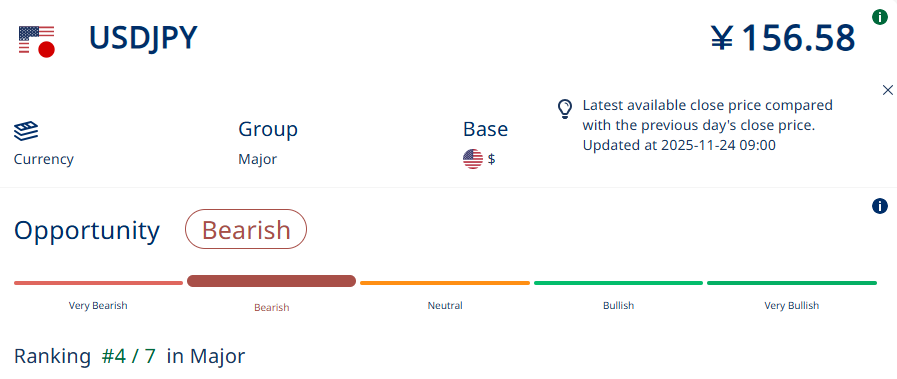
USD/JPY Market Sentiment / Source: Acuity
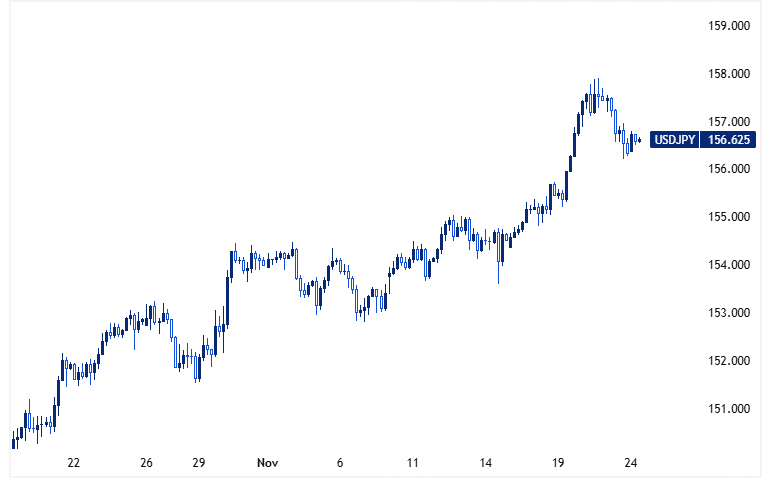
USD/JPY Chart / Source: TradingView
Why its Trending?
The Japanese yen continues to slide as the Bank of Japan delays its next rate hike and Prime Minister Takaichi’s fiscal stimulus adds further pressure. With the currency edging toward levels that previously triggered action, talk of a potential FX intervention is heating up. Officials have started signalling that they may step in if the yen’s decline accelerates.
Meanwhile, the US dollar is holding its ground as traders weigh the Fed’s mixed messaging. New York Fed President John Williams suggested a December rate cut is on the table, arguing that labour market risks now outweigh inflation concerns. Markets took note, pricing in a 69% chance of a 25-basis-point cut next month, up sharply from 44% last week. But the debate isn’t settled. Boston Fed President Susan Collins said she still hasn’t reached a decision on the next move.


