

 ar
With a new trading week comes new opportunities. So, we’ve gathered insights for the week ahead that highlight the current trends, scheduled events and potential movers to watch. Let’s get started.
Calendar Events
- Eurozone Final Manufacturing PMI – Nov 3
- UK Final Manufacturing PMI – Nov 3
- US ISM Manufacturing PMI – Nov 3
- Reserve Bank of Australia Interest Rate Decision – Nov 4
- US JOLTS Job Openings (Tentative) – Nov 4
- Eurozone Final Services PMI – Nov 5
- Eurozone PPI – Nov 5
- US ADP Employment Change – Nov 5
- US ISM Services PMI – Nov 5
- Bank of England Interest Rate Decision – Nov 6
- US Average Hourly Earnings (Tentative) – Nov 7
- US Non-Farm Payrolls (Tentative) – Nov 7
- US Unemployment Rate (Tentative) – Nov 7
- Canada Unemployment Rate – Nov 7
Top Things to Watch
Government Shutdown Stirs Uncertainty in Markets
The ongoing US government shutdown continues to cloud market sentiment, adding uncertainty as crucial economic data releases remains on hold. With few official indicators available to assess economic momentum, traders have turned their focus to private-sector reports like ADP employment, ISM PMIs, and corporate earnings for guidance.
This data blackout has heightened volatility in both the US dollar and Treasury yields, while risk appetite stays fragile amid growing concerns about fiscal stability and the potential impact on upcoming budget and debt ceiling discussions.
RBA, BOE Set to Announce Rate Decisions
This week, upcoming central bank rate decisions will be announced from the Reserve Bank of Australia and the Bank of England. The RBA will meet on Tuesday is expected to keep rates at 3.6%, balancing persistent inflationary pressures against signs of slowing household spending and softer labor demand. Markets will look for guidance on how long policymakers intend to keep rates restrictive as inflation remains above target.
The Bank of England is expected to keep rates unchanged on Thursday ahead of the UK’s Autumn Budget. Policymakers are caught between high inflation and sluggish economic growth, with fiscal policy also showing concerns. With consumer spending slowing and business investment subdued, investors are now focused on when the BoE might begin easing policy, though the timing remains uncertain heading into 2026.
Earnings This Week: Palantir, AMD, Shopify & McDonald’s
Earnings season continues next week with Palantir on November 3, AMD and Shopify on November 4, and McDonald’s on November 5. Markets will be focused on Palantir’s AI and government contracts, AMD’s chip demand, Shopify’s e-commerce growth, and McDonald’s consumer trends for signals on corporate performance and market sentiment.
Trending Now: GBP/JPY
Source: Acuity
GBP/JPY Chart / Source: TradingView
Why It’s Trending?
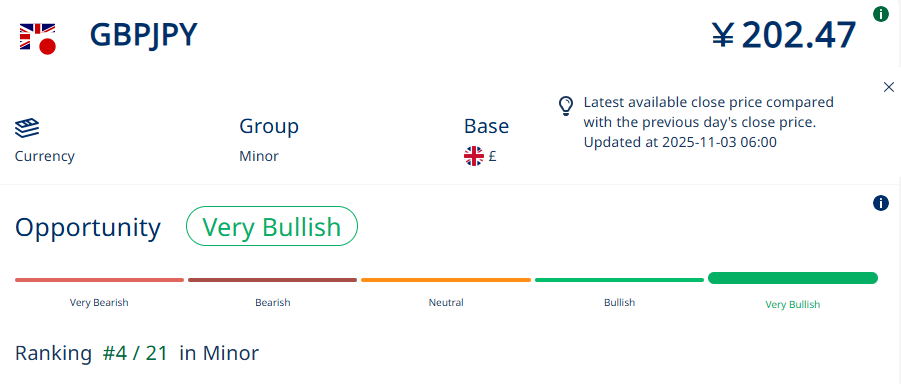
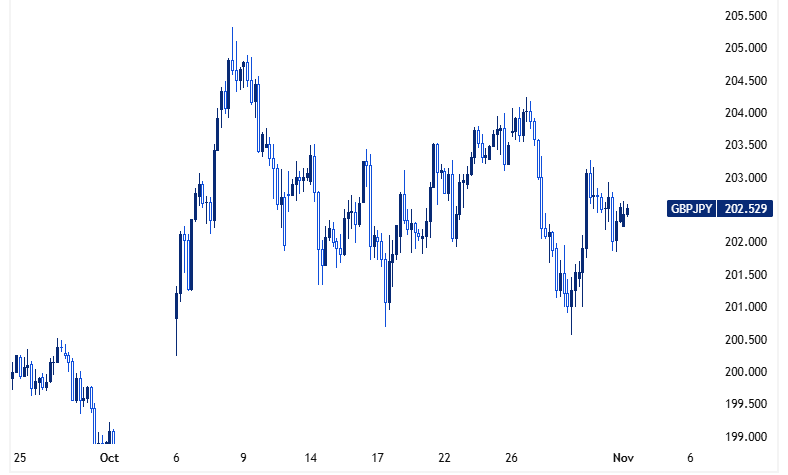
The Pound remains strong against the Yen after the Bank of Japan left interest rates unchanged at 0.5% last week, with dovish remarks from the BOJ pressuring the Yen. The GBP/JPY pair rebounded from three-week lows near 200.57 to 202.50.
BOJ Governor Kazuo Ueda maintained a dovish stance, noting that economic growth remains modest and inflation is expected to rise gradually, but he downplayed the need for immediate rate hikes. This cautious tone disappointed investors, sending the Yen lower.
The Pound’s gains against the Yen might be at risk due to downgraded growth forecasts from the UK’s Office for Budget Responsibility and fiscal concerns ahead of the Autumn Budget, due on November 26. Meanwhile, markets are pricing in a rate hold from the Bank of England on Thursday, with an unclear path on rate cuts in 2026.


