

 ar
Markets are entering the week in wait-and-watch mode. Geopolitics is keeping oil elevated, while a heavy wave of data will decide whether growth is holding up, or starting to crack.
This isn’t panic mode, but it’s not confidence either. Let’s break down everything to watch this week.
Calendar Events
- UK Quarterly GDP – Mar. 31
- Eurozone Flash CPI – Mar. 31
- Canada Monthly GDP – Mar. 31
- US JOLTS Job Openings – Mar. 31
- US CB Consumer Confidence – Mar. 31
- US ADP Employment Change – Apr. 1
- US Retail Sales – Apr. 1
- US ISM Manufacturing PMI – Apr. 1
- US Non-Farm Payrolls – Apr. 3
- US Unemployment Rate – Apr. 3
- US Average Hourly Earnings – Apr. 3
Top Things to Watch
Middle East: Still No Off Switch
Geopolitical tensions remain elevated even after US President Trump extended the deadline for Iran to reopen the Strait of Hormuz. Tehran said no. Four weeks in, and there’s still no off-ramp in sight.
Oil is hovering near $100, and is stuck in a tension premium that won’t let go. The US floated a pause on targeting Iranian energy facilities, but a pause isn’t a resolution. Markets know the difference. Until there’s a real deal on the table, every headline is a potential catalyst.
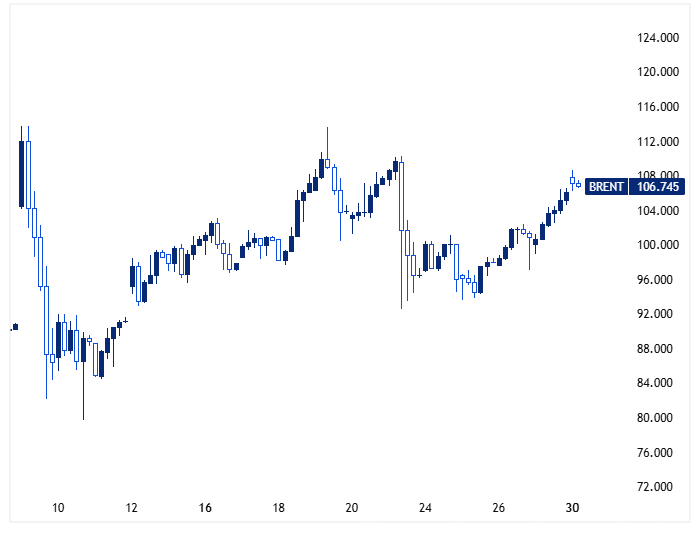
Global markets are bleeding.
The Iran war has erased trillions in market value, a shock so massive it rivals the combined economies of Germany, the UK, and India. Geopolitics isn’t noise. It’s the biggest market mover.
Markets Slide as Oil Surge and Geopolitics Shake Risk Sentiment
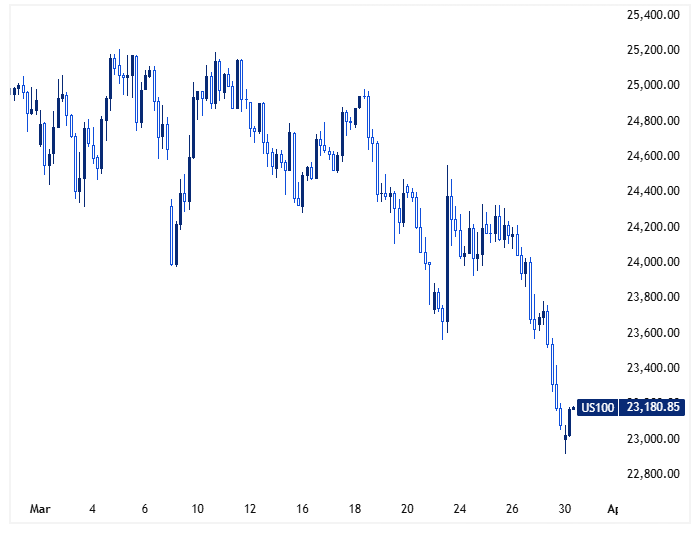
US stocks sold off sharply on Friday as rising tensions in the Strait of Hormuz, fueling energy supply fears. The Dow dropped 1.73% (793 pts) into correction territory, while the S&P 500 fell 1.67% to a seven-month low and the Nasdaq slid 2.15%.
Markets extended their losses last week, with the S&P 500 down 2.1%, the Nasdaq 3.2%, and the Dow 0.9%. The Nasdaq is now nearly 13% below its peak, the Dow is down 10%, and the S&P 500 has fallen 8.7% from its record high.
Looking ahead, markets are likely to stay volatile, with oil prices and geopolitical developments continuing to drive sentiment.
US Data Offers a Full Week of Signals
This is one of those weeks where the data flow can shape the broader market narrative.
JOLTS and Consumer Confidence kick things off, then ADP employment data, Retail Sales, and ISM Manufacturing pile in mid-week. Friday brings US labor market data and ISM Services.
After the previous report showed job losses of 92,000 and higher unemployment, markets will be watching closely for signs of either stabilization or further weakness, with the outcome likely to play a key role in shaping expectations for the Fed’s policy path.
Eurozone CPI: Almost There, But Not Quite
Inflation in the Eurozone was supposed to be fading. Instead, it edged back up to 1.9% in February, services prices picked up again, and core moved to 2.4%. Not alarming but not the clean story markets wanted either.
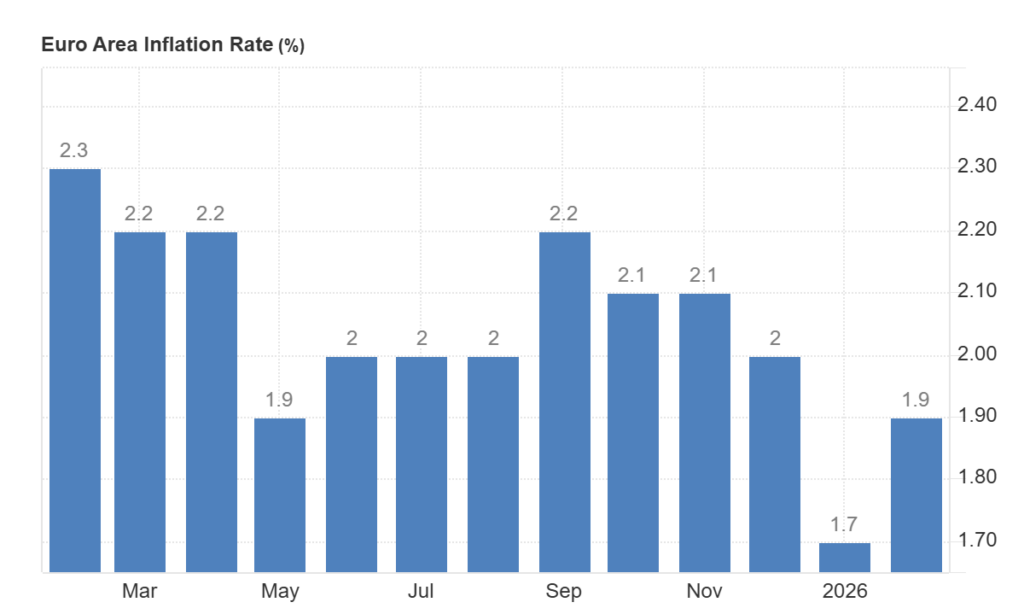
Flash CPI this week will show whether March was a bump or a signal. The ECB would love a straight line down. But unfortunately, they’re not getting one.
UK GDP Can’t Afford to Disappoint
The UK economy has been walking on a tightrope of sluggish growth, stubborn inflation, and a Bank of England that can’t fully commit either way.
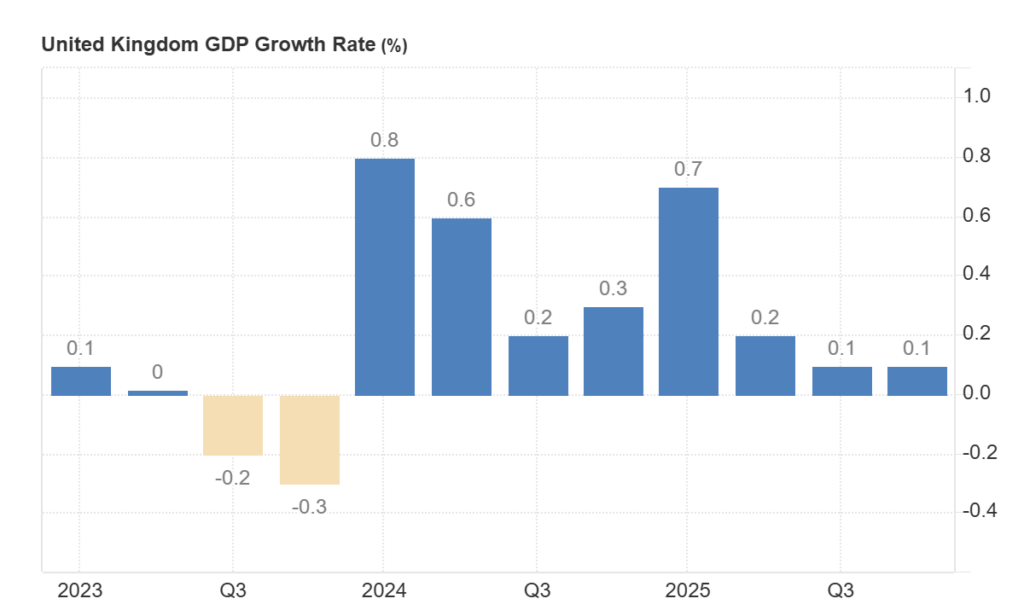
That puts extra focus on this week’s Q4 GDP number. A soft reading would reinforce the sense that the economy is struggling for momentum. A stronger one would offer some relief, but probably not enough to remove the bigger questions.


