

 ar
A new week begins with markets focused on geopolitics and key data.
Middle East tensions are keeping oil prices elevated, adding to inflation risks.
At the same time, central banks have held rates steady but signaled they may keep rates higher or tighten more if price pressures persist.
PMIs and inflation data this week will be key in shaping moves across currencies and global markets.
Let’s break down what to expect in the week ahead.
Calendar Events
- Eurozone HCOB PMI – Mar. 24
- UK S&P PMI – Mar. 24
- US S&P PMI – Mar. 24
- Australia CPI – Mar. 25
- UK CPI – Mar. 25
Top Things to Watch
Central Banks on Alert as Oil Shock Fuels Inflation Risks
Global central banks kept interest rates unchanged last week but signaled readiness to tighten policy if inflation resurges, as escalating Middle East tensions push energy prices higher.
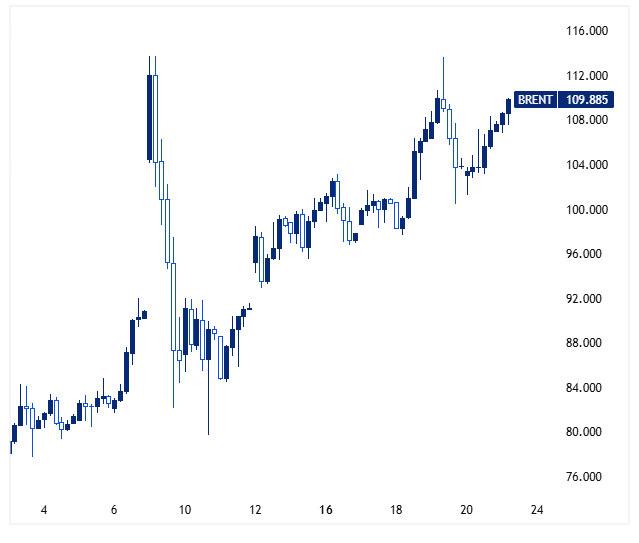
The Fed, ECB, BOE, BOJ and others warned that sustained oil price increases could spill into broader inflation, raising concerns about a potential stagflation environment. Oil prices are now up 8% since Friday’s low and up 50% since the start of the conflict.
While policymakers remain cautious amid uncertain growth, markets have begun to price in the risk of future rate hikes, highlighting how geopolitical shocks are once again driving the macro narrative.
Gold and Silver Remain Pressured as Oil Rally Reignites Inflation Narrative
Gold fell 8%, extending last week’s 10% plunge, its steepest weekly drop since 1983, as Middle East tensions and rising oil prices fueled inflation fears.
Silver dropped 10%, adding to last week’s 15% decline and marking a fourth consecutive weekly loss.
The sharp move in metals reflects mounting inflation concerns, with markets increasingly pricing in a potential Fed rate hike later this year while other major central banks signal readiness to tighten if pressures persist.
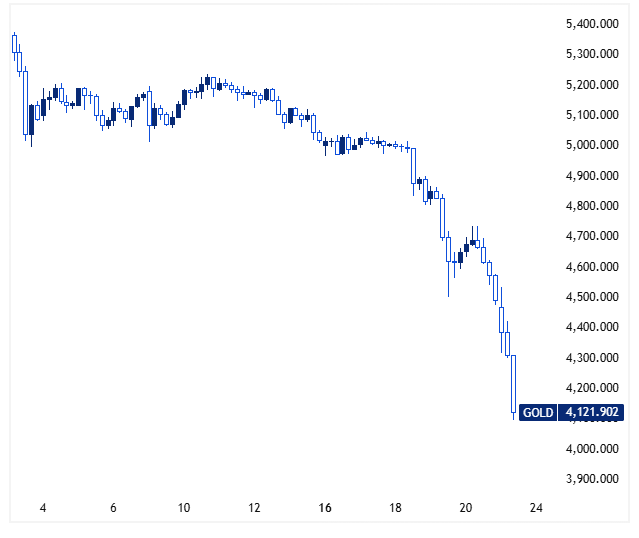
Gold 4H Chart / Source: TradingView
Global PMIs to Offer a Snapshot of Growth
Global PMI data, especially in the Eurozone, UK, and US will provide a broad and timely snapshot of business activity across major economies on Tuesday.
Investors will be watching closely for signals from both manufacturing and services sectors to assess whether growth momentum is stabilizing or showing signs of slowing, with the data helping shape expectations around the global economic outlook.
UK Inflation Data to Guide Policy Expectations
UK’s February inflation data on Wednesday will be a key focus, with the annual CPI rate was last recorded at 3% in January 2026, down from 3.4% and marking its lowest level since March 2025.
The continued easing trend adds to expectations around policy direction, where any surprise could shift how markets price the balance between cooling inflation and still-fragile growth.
Australia CPI in Focus
Australia’s CPI data on Wednesday will be a key focus as markets assess inflation trends and underlying price pressures, especially after the Reserve Bank of Australia raised rates by 25bps to 4.10%, marking a second consecutive hike amid persistent inflation and rising energy-driven risks.
The release could further shape expectations for the RBA’s policy outlook, particularly if price pressures continue to show signs of persistence or begin to moderate.


